Over 1.5 Million International Followers and Readers have engaged our various curated digests which provides Insights and Ideas from leading global investors, economists, scientists, experts and media; focusing on Humanity's "BIG 7 Es" as they pertain to individual wealth issues. Meshing the best and brightest minds to provide our world leading - - "INVEST DIFFERENT" - Stayin the Know, Ahead of Markets, Decide Wisely...
Beijing 'may be playing risky game in stock rally'
THE Chinese stock market is on fire after a rally sent the benchmark equity index to a seven- year high, but experts say Beijing could be playing a risky game in its bid to revive the economy through a boost to stocks.
After a previous market crash wiped out more than US$3.5 trillion (S$4.7 trillion) from the market's 2007 peak, a new bull run has taken hold. The Shanghai index has more than doubled since the run-up began last July.
While stocks have been gaining on the back of expectations of new measures to spur the slowing Chinese economy, experts say this rally is not without a key cheerleader - Beijing itself. Read More.
The price-to-cashflow ratio (PCF) is a popular metric among value investors. Many believe that using cashflow, rather than accounting earnings, delivers a truer picture of a company’s business performance, which in turn leads to better investment performance.
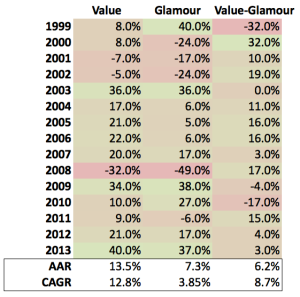
Set out below are the results of two Fama and French backtests of the cashflow yield (the inverse of the PCF ratio) data from 1951 to 2013. As at December 2013, there were 2,526 firms in the sample. The value decile contained the 269 stocks with the highest earnings yield, and the glamour decile contained the 311 stocks with the lowest earnings yield. The average size of the glamour stocks is $4.74 billion and the value stocks $4.80 billion. (Note that the average is heavily skewed up by the biggest companies. For context, the 2,526th company has a market capitalization today of $272 million, which is much smaller than the average, but still investable for most investors). Stocks with negative cashflow were excluded. Portfolios are formed on June 30 and rebalanced annually.
Annual and Compound Returns (Portfolio Constituents Weighted by Market Capitalization)
In this backtest, the two portfolios are weighted by market capitalization, which means that bigger firms contribute more to the performance of the portfolio, and smaller firms contribute less. Here we can see that the value decile has comprehensively outperformed the glamour decile, returning 16.7 percent compound (18.6 percent in the average year) over the full period versus 9.3 percent for the glamour decile (11.5 percent in the average year). - Read More
Remember an Old Lesson
Platinum Advice:
The secret of successful investing - then the rest is up to you. Oh yeah, and never marry the markets.
"Cash Flow, Cash Flow, Cash Flow"
That stated, these markets are way over priced as the cash flow values make no sense. Looks like 2000 all over again if we run out of those bigger fools.